Last week delivered a masterclass in range-bound chop across US indices, with the Dow and S&P 500 closing marginally lower despite Friday's stronger-than-expected payrolls data. Metals stole the show—gold and silver both surged over 3%—whilst USD/JPY collapsed nearly 2%, signalling renewed risk-off flows beneath the surface calm.
Last Week in Review
Last week was a tale of two markets. US indices ground sideways—the S&P 500 edged up just 0.42% to 7,718.60, the Dow added 0.43% to 53,414.25, and the NASDAQ scraped 0.30% to 29,544.15. The FTSE 100 was virtually flat at 10,831.09, up a mere 0.06%. Beneath the surface, however, we saw significant moves: gold surged 2.96% to 4,476.60, silver rallied 3.30% to 66.75, and USD/JPY collapsed 2.32% to 156.03. The Friday payrolls beat (162,000 vs 53,000 expected) initially sparked rate hike chatter, but risk appetite faded into the close. Oil also pushed higher—WTI up 1.40% to 91.48—as geopolitical tensions in the Middle East simmered. Overall, it was a choppy, directionless week for equities, with defensive flows dominating.
US30 (Dow Jones) — Weekly Outlook
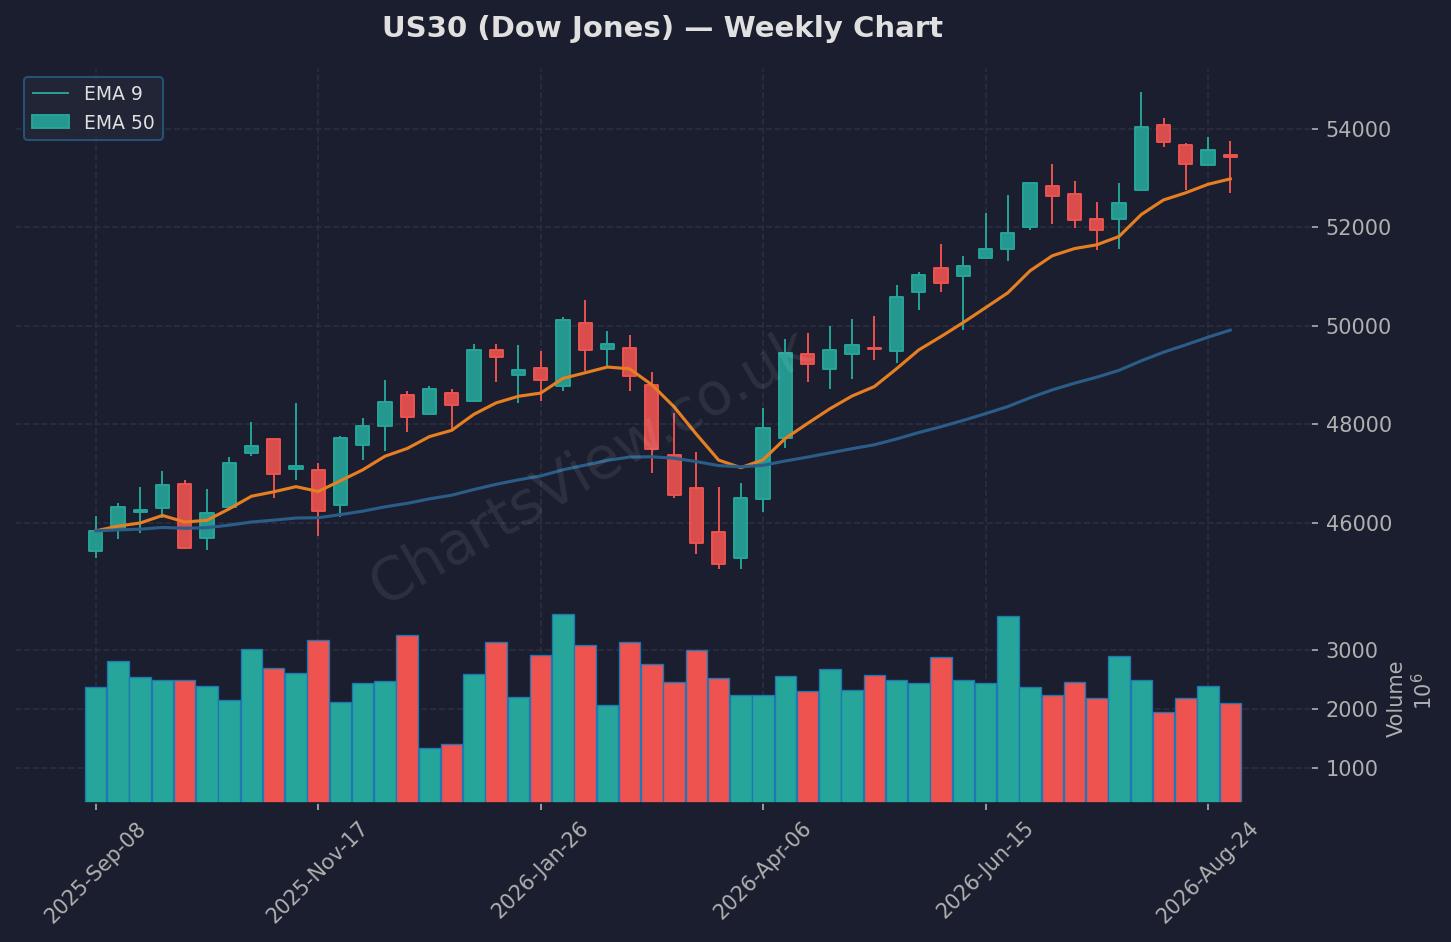
US30 (Dow Jones) Weekly Chart — EMA 9 (orange) & EMA 50 (blue) | Source: ChartsView
US30 closed the week at 53,414.25, down 0.51% from the prior close of 53,686.11, printing a small bearish candle with a wick rejection off the 5-day high at 53,746.50. Price remains trapped in a wide range between the 5-day low at 52,691.31 (key support) and the 53,746.50 resistance zone. My bias this week is cautiously bearish below 53,686—the previous close acts as near-term resistance, and if we fail to reclaim it, I'm watching for a retest of 52,691 support. A clean break and close below 52,691 opens the door to further downside toward 52,000 psychological. However, if US30 reclaims 53,686 and pushes through 53,746, that flips me neutral-to-bullish, targeting a run toward 54,000. The Friday payrolls data should have been rocket fuel for indices, but the failure to follow through tells me sellers are still in control. I'm waiting for a decisive break either way before committing—no trades in the middle of the range. Invalidation of the bearish bias is a daily close above 53,746.
NAS100 (NASDAQ) — Weekly Outlook
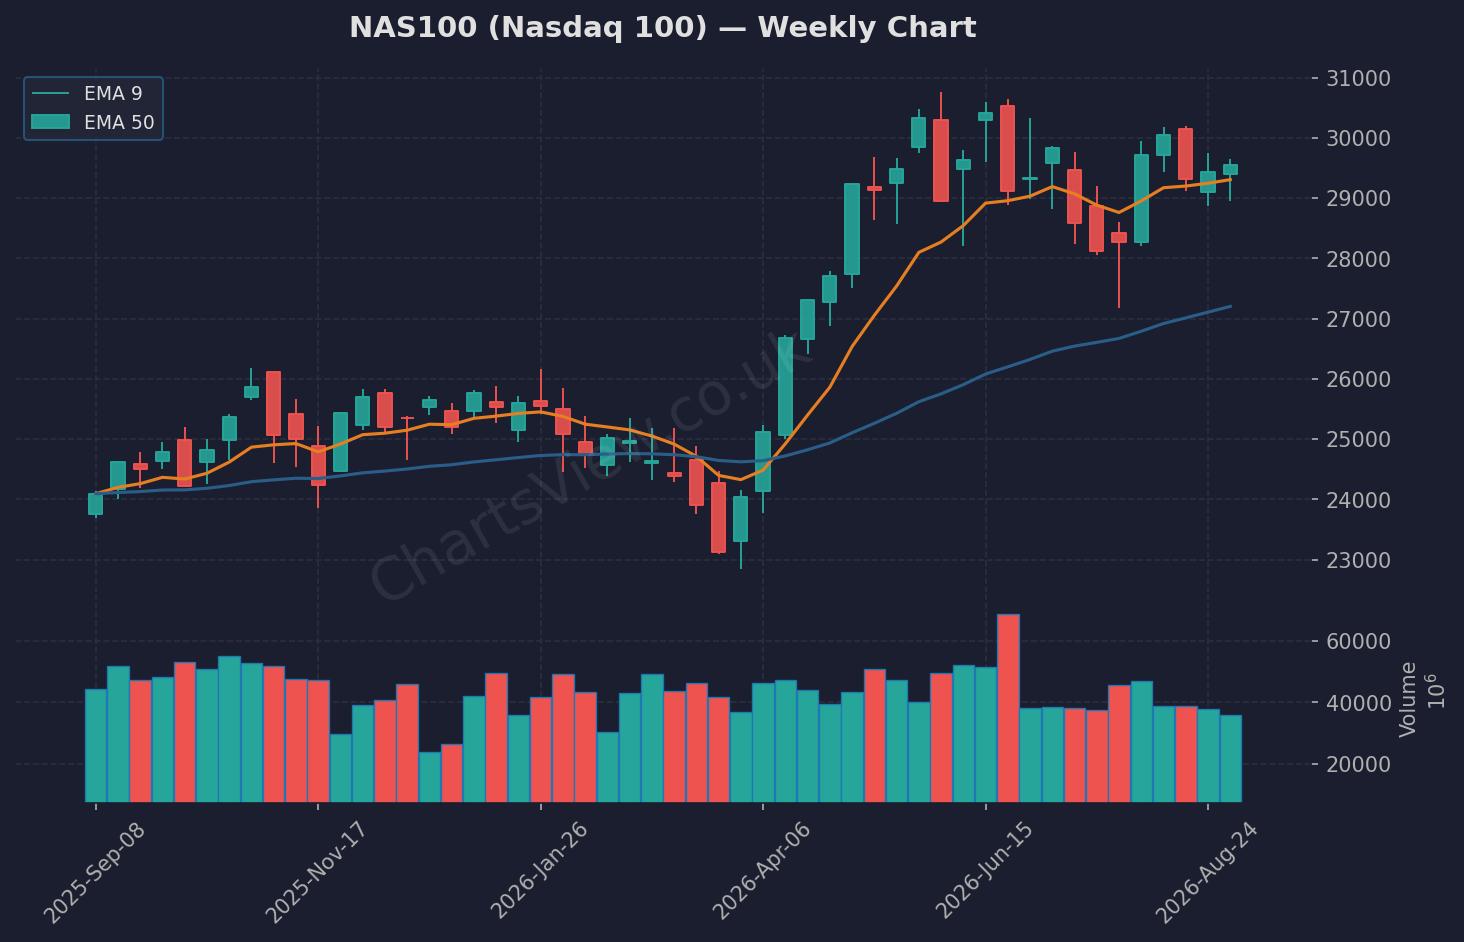
NAS100 (Nasdaq 100) Weekly Chart — EMA 9 (orange) & EMA 50 (blue) | Source: ChartsView
NAS100 closed at 29,544.15, up a modest 0.21% on the week, printing an inside bar within the prior week's range. The 5-day high at 29,655.22 is the immediate resistance to watch, whilst the 5-day low at 28,953.26 marks critical support. Tech has been resilient, but it's also failed to break out despite the AI data centre narrative continuing to dominate headlines. My bias is neutral-to-slightly-bullish—if NAS100 holds above 29,482 (previous close) and reclaims 29,655, I'm looking for longs targeting 30,000 psychological. However, a break below 28,953 would be a significant technical failure and could trigger a flush toward 28,500. The lack of conviction last week suggests traders are waiting for a catalyst—likely this week's economic data or any fresh Fed commentary. I'm not forcing trades here; I want to see a clear break and retest of either 29,655 or 28,953 before entering.
Quick Takes
S&P 500: Closed at 7,718.60, marginally lower on the week—watching 7,747 resistance and 7,611 support; no trade until we break out of this tight range.
Gold: Absolute beast mode—up 2.96% to 4,476.60, testing the 5-day high at 4,510.00; if we clear 4,510, next stop is 4,600, but I'm cautious of a pullback after such a vertical move.
GBP/USD: Down 0.27% to 1.3513, rejected from 1.3561 resistance; cable looks heavy, and a break below 1.3475 opens 1.3400.
WTI Oil: Up 1.40% to 91.48, eyeing the 5-day high at 93.14—geopolitical risk premium is back, and a push through 93.14 targets 95.00.
Key Events This Week
- Monday, 06:00 GMT — Germany Industrial Production (Jul): Forecast 0.3% vs 0.2% prior. A beat could support European risk appetite, but Germany's industrial sector has been weak—watch for downside surprises.
- Monday, 06:00 GMT — UK Lloyds House Price Index (Aug): Forecast 0.2% MoM. UK housing data has been soft; any weakness here adds to the dovish BoE narrative.
- Monday, 12:30 GMT — UK Chancellor John Healey Speech: Healey is expected to discuss the UK economy "turning a corner" ahead of the Budget. Watch for any fiscal policy hints that could move GBP and the FTSE.
- Monday, 23:01 GMT — UK BRC Retail Sales Monitor (Aug): Forecast 1.2% YoY vs 1.0% prior. Retail sales have been sluggish—any miss could weigh on GBP further.
The biggest risk event this week is the Chancellor's speech—any dovish fiscal commentary or warnings about debt could spook UK assets and ripple into broader risk sentiment.
The Week Ahead — My Game Plan
I'm sitting on my hands until US30 and NAS100 give me a clear directional break. The range-bound chop last week was frustrating, and I'm not interested in getting chopped up further. My bias leans cautiously bearish on US30 below 53,686, but I need confirmation—a break of 52,691 support is my trigger. On NAS100, I'm waiting for a reclaim of 29,655 before considering longs. Gold and silver are extended, so I'm watching for pullbacks rather than chasing. This week's economic calendar is light, but the Chancellor's speech and any fresh Fed commentary could be the catalyst we need. As always, risk management is king—no trade is worth blowing up your account over. Let the market come to you.
Written by Remo, founder of ChartsView. This outlook reflects personal analysis and does not constitute financial advice. Always do your own research and manage your risk.